Secured vs Unsecured Loans in India Explained
What collateral means, how secured and unsecured credit differ on risk and cost structure, and which questions to ask before you borrow.
By FinanceBlogg Editorial Team
Published 4 min read
Editorially reviewed by FinanceBlogg Editorial Team on . How we review articles
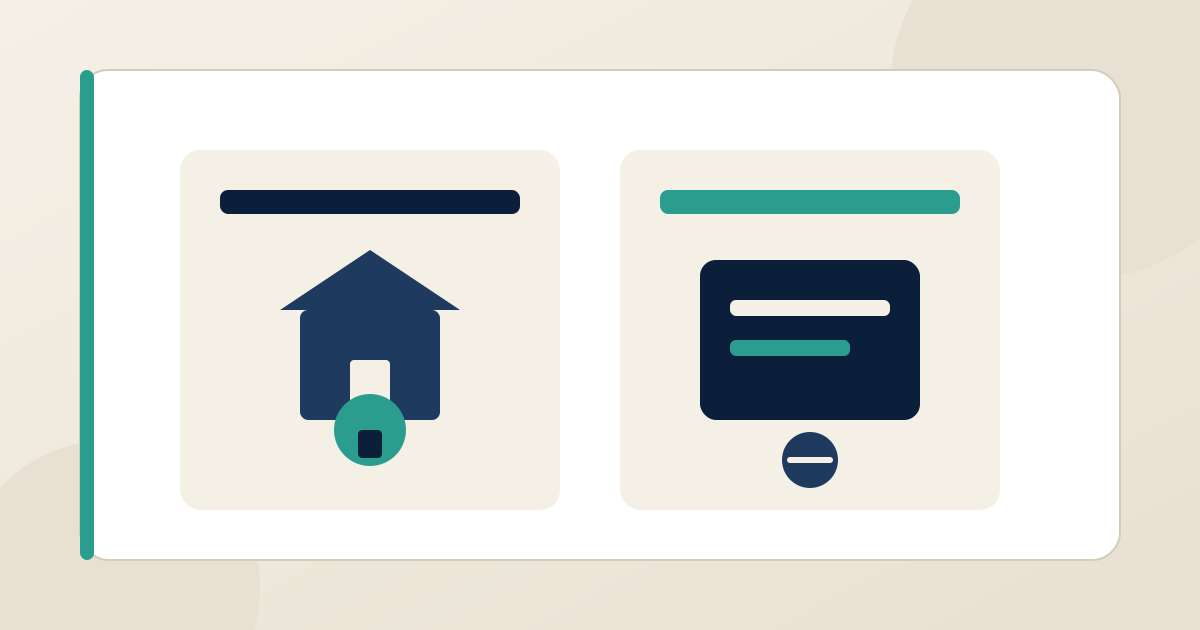
In India, retail credit is often described as secured or unsecured. The difference is not marketing language: it is whether the lender has a legal claim on a specific asset (collateral) if you default, versus relying mainly on your creditworthiness and contract remedies without that asset pledge.
This article explains the distinction. It does not recommend any loan product or lender.
What “secured” means
Collateral is an asset you offer (or that is financed and then charged) so the lender has a defined recovery path if dues are not paid as agreed. Common household examples in India include:
- Home loans (property as security)
- Vehicle loans (the vehicle as security)
- Loans against deposits, gold, or securities (where the pledged asset is specified)
“Secured” does not mean “safe for the borrower.” It means the lender’s risk is partly covered by the asset. If you cannot pay, you may face recovery action against that collateral under applicable law and the loan contract.
What “unsecured” means
Unsecured credit typically includes many personal loans and most credit-card outstanding balances: there is no house or car officially pledged for that facility. The lender assesses ability and willingness to pay—income documents, banking behaviour, and credit score / bureau history.
Without collateral, lenders may price for higher credit risk, set stricter eligibility, or limit ticket size. That is a general risk logic—not a promise that every unsecured loan is “expensive” or every secured loan is “cheap.”
Side-by-side: what actually changes for households
| Dimension | Secured (typical) | Unsecured (typical) |
|---|---|---|
| Collateral | Yes, as per agreement | No pledged asset for that facility |
| Documentation | Often includes asset papers / valuation | Focus on income, KYC, bureau |
| Borrower downside on default | Asset may be at risk | Contractual recovery without that pledge; still serious |
| Product examples (illustrative categories) | Home, auto, gold loan | Personal loan, credit card |
Exact pricing, processing fees, insurance tie-ins, and foreclosure rules are product- and lender-specific. Compare sanction letters, not social-media tables.
Interest, EMI, and rate type still matter
Whether secured or unsecured, you still need to understand:
- Interest rate and whether it is floating or fixed — loan interest rates
- EMI construction — how loan EMI is calculated
- Prepayment / foreclosure rules — how prepayment and foreclosure work
A lower headline rate on a secured loan can still be costly if fees, tenure, or reset clauses are poorly understood. An unsecured loan with a clear tenure and no surprise charges can be simpler for a short, planned need—if repayment is realistic.
Questions to ask before you sign
- Is this facility secured or unsecured in the sanction letter?
- If secured, what asset is charged, and what happens on default?
- What is the all-in cost (interest + fees + mandatory add-ons disclosed)?
- What is the rate reset mechanism if floating?
- Can you prepay, and at what cost?
- How will missed EMIs be reported to credit bureaus?
Bottom line
Secured vs unsecured is about collateral and risk allocation—not a moral ranking of “good” and “bad” loans. Match the structure to a repayment plan you can keep, read the contract, and treat asset pledges with the seriousness they deserve.
Related reading
Sources and further reading
We link to official and primary sources wherever possible. Rules and rates change, so check the latest version on the source website.
- Reserve Bank of India — Reserve Bank of India
- RBI Financial Education — Reserve Bank of India
- How loan EMI is calculated (FinanceBlogg) — FinanceBlogg
About the author
FinanceBlogg Editorial Team
Editorial Team
The FinanceBlogg editorial team researches and writes educational explainers on personal finance in India. Articles are based on official sources such as the Reserve Bank of India, SEBI, IRDAI and the Income Tax Department, and are updated when rules change.
View profile and articlesSpotted an error? Read our corrections policy and tell us.
Related articles
Floating Rate vs Fixed Rate Loans in India: What Changes for Your EMI
Floating vs fixed rate loans in India explained: how EMIs and tenure can change, reset clauses to read, and questions to ask—without product tips.
· 4 min read
How Loan Prepayment and Foreclosure Work
What loan prepayment and foreclosure mean in India, how extra payments change interest, typical charges, and what to check in your sanction letter.
· 6 min read
How a Loan EMI Is Calculated
How a loan EMI is calculated in India, why early EMIs are mostly interest, and how tenure and rate change what you repay.
· 4 min read